
Highlights
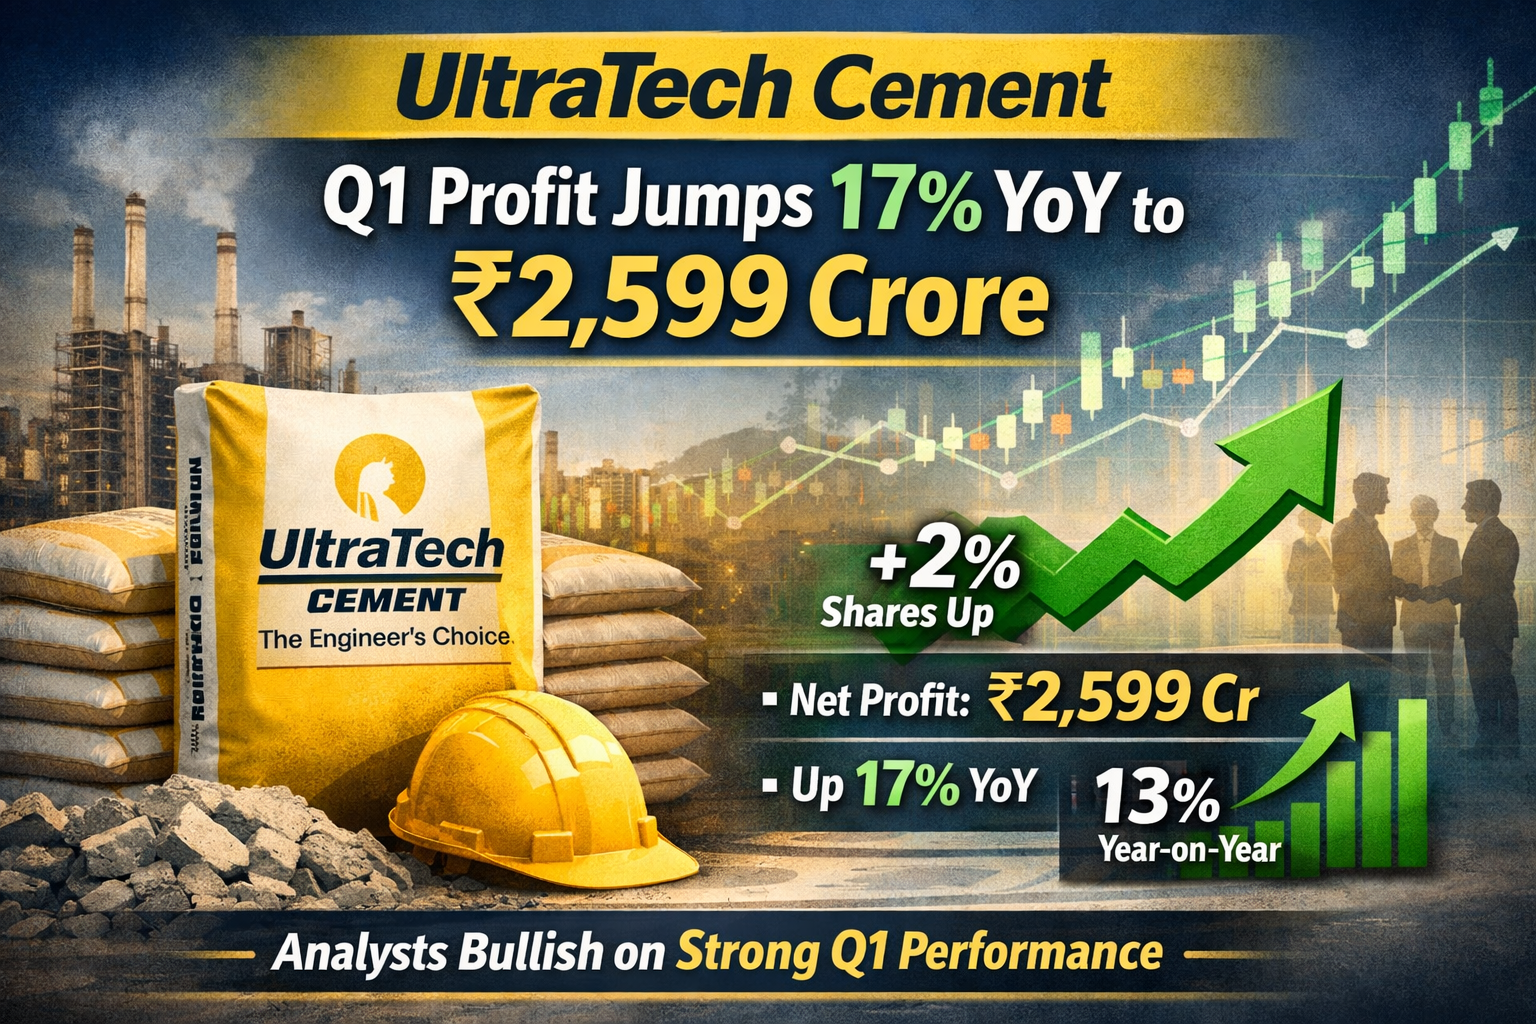
- Strong Bottom-Line Growth: UltraTech Cement reported a 17% year-on-year increase in consolidated net profit, reaching ₹2,599 crore for the first quarter.
- Revenue and Volume Expansion: Consolidated revenue from operations jumped 16% to ₹24,648 crore, backed by double-digit volume expansion in domestic grey cement.
- Positive Stock Market Reaction: Investors responded favorably to the impressive performance, driving the UltraTech Cement Share up by nearly 2% in intra-day trade.
Indian building materials giant UltraTech Cement has delivered a stellar performance for the first quarter of the fiscal year. The consolidated net profit surged 17% year-on-year to reach ₹2,599 crore, compared to ₹2,226 crore in the corresponding period of the previous fiscal year. Driven by sustained infrastructure investments, active commercial real estate expansion, and healthy residential construction across urban and rural markets, the flagship Aditya Birla Group enterprise maintained solid operational momentum throughout the quarter.
Following the announcement of these strong quarterly metrics, investor sentiment turned overwhelmingly positive on Dalal Street. The market reaction was swift, with the UltraTech Cement Share advancing nearly 2% to hit an intra-day high. Equity analysts and institutional investors highlighted the company’s ability to maintain healthy margins and achieve double-digit sales volume growth despite seasonal fluctuations and inflationary cost pressures across logistics and fuel sectors.
The official release of the Q1 Results demonstrated a comprehensive improvement across both top-line and operational indicators. Consolidated revenue from operations rose by 16% year-on-year to ₹24,648 crore, up from ₹21,275 crore reported during the same quarter of the prior year. This broad-based top-line expansion was primarily anchored by a 12% rise in consolidated grey cement sales volumes, which reached 41.31 million tonnes during the April–June quarter.
Operating profitability also witnessed a robust trajectory during the quarter under review. Consolidated EBITDA grew 12% year-on-year to ₹5,146 crore, compared to ₹4,591 crore recorded in the same period last year. On a unit basis, operating EBITDA per tonne improved slightly to ₹1,214. The management attributed this earnings durability to relentless execution, strict fixed-cost controls, optimized distribution networks, and an increased share of green power in its manufacturing mix.
To cater to growing construction demand across the subcontinent, the company has continued its aggressive capacity expansion strategy. During the quarter, UltraTech commissioned additional grey cement production capabilities, bringing its total domestic installed capacity past 200 million tonnes per annum (MTPA) and consolidated global capacity to over 205 MTPA. This aggressive scaling positions the cement manufacturer to capture incremental market share as public infrastructure allocations continue to rise.
Market watchers continuously tracking the UltraTech Cement Share note that the company’s integrated ecosystem provides a distinct competitive moat. Alongside its core cement business, UltraTech’s specialized segments including ready-mix concrete (RMC) and construction chemicals have logged strong double-digit growth rates. Furthermore, the company’s strategic integration of acquired assets, such as India Cements, has added significant regional revenue synergies to its overall portfolio.
In addition to expanding its traditional cement footprint, UltraTech is actively diversifying into allied building materials. The management reiterated its upcoming entry into the wires and cables business, backing the initiative with a planned capital expenditure of ₹1,800 crore. Over ₹880 crore has already been committed as of June, setting the stage for a commercial launch in the third quarter. This vertical integration leverage is expected to deepen the company’s market penetration across its retail distributor network.
Following the detailed breakdown of the Q1 Results, several leading domestic and global brokerages reiterated their bullish stance on the cement major. Analysts underscored the company’s structural advantages, including rising asset turnover, disciplined capital allocation, and industry-leading cost management. Many research firms raised their target prices for the stock, citing strong volume visibility and expected cement price stability after the monsoon season.
Looking ahead, the long-term outlook for the UltraTech Cement Share remains underpinned by favorable macroeconomic trends and government-backed infrastructure initiatives. As housing demand stays firm and commercial development accelerates across tier-2 and tier-3 cities, the market leader is well-positioned to sustain its profitable growth trajectory. With an expanding manufacturing footprint and disciplined financial execution, UltraTech continues to set the benchmark for the Indian cement industry.
Visit Augmenting Money for the most recent information.
Leave a Reply